


The financial services sector has undergone a radical transformation over the past decade, with technology in finance evolving from a competitive advantage to an essential foundation for survival. From artificial intelligence-powered risk assessment to blockchain-based settlement systems, financial institutions are deploying advanced technologies across every operational layer. This shift has accelerated dramatically in 2026, driven by regulatory pressures, customer expectations, and the need for operational resilience in an increasingly digital economy.
The Current State of Technology in Finance
Financial technology has matured beyond simple digitization of paper processes into sophisticated systems that fundamentally reimagine how value moves through the economy. Banks, insurers, asset managers, and payment providers now rely on interconnected technology stacks that combine cloud computing, machine learning, distributed ledgers, and advanced analytics.
The integration of technology in finance has become so pervasive that the Financial Stability Board’s consultation report on AI adoption outlines twelve sound practices specifically addressing how financial institutions should govern, deploy, and monitor artificial intelligence systems. These guidelines reflect the reality that technology decisions in finance now carry systemic risk implications.
AI and Machine Learning Applications
Artificial intelligence stands as the most transformative force in contemporary financial services. Financial institutions are deploying machine learning models across credit underwriting, fraud detection, algorithmic trading, customer service, and regulatory compliance.
The U.S. Treasury’s AI Risk Management Framework, released in February 2026, provides operational guidance for banks implementing AI systems. This framework addresses critical concerns around model governance, data quality, explainability, and third-party dependencies that arise when financial decisions rest on algorithmic outputs.
Key AI applications currently transforming finance include:
- Credit risk modeling that analyzes thousands of data points beyond traditional credit scores
- Real-time fraud detection systems processing millions of transactions per second
- Conversational AI handling customer inquiries with natural language understanding
- Portfolio optimization algorithms that continuously rebalance investments
- Regulatory compliance automation scanning communications and transactions for violations
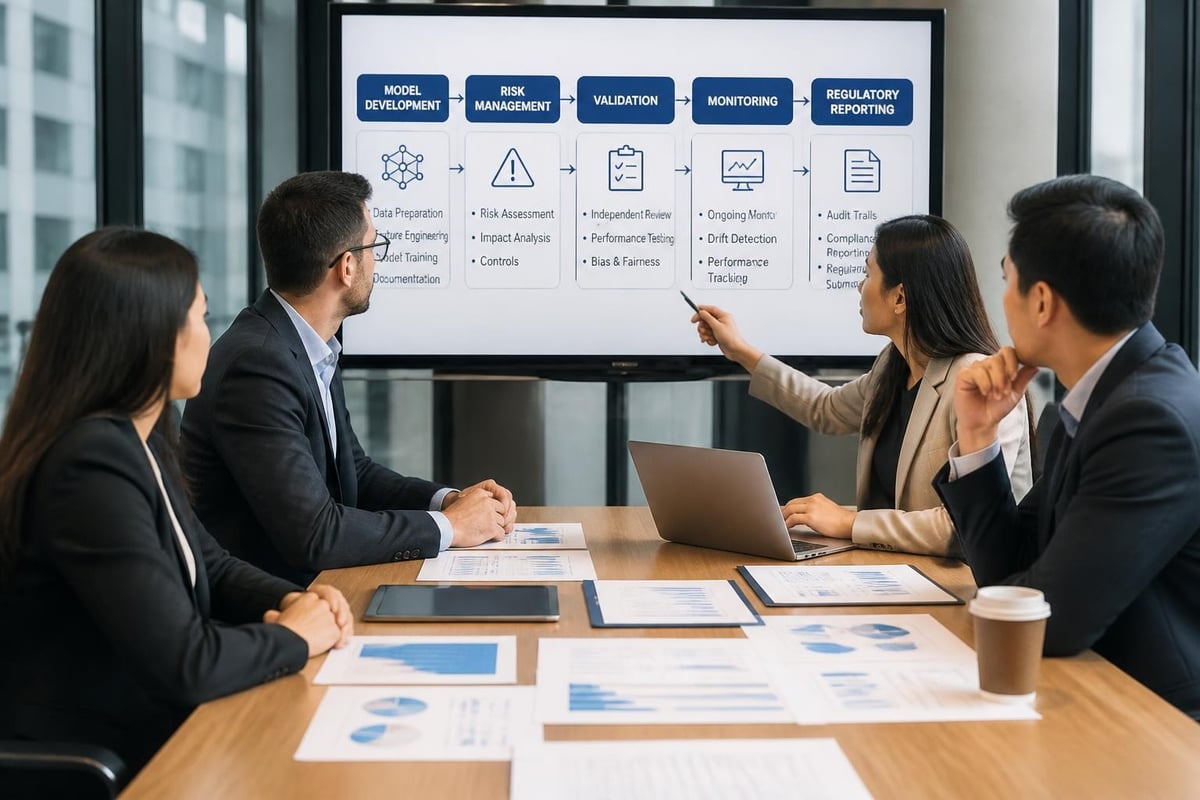
The BIS FSI Insights paper on supervisory approaches to AI data use highlights critical infrastructure challenges including data privacy, quality assurance, security protocols, and managing dependencies on third-party data providers. These concerns become especially acute as AI systems make decisions affecting credit access, insurance pricing, and investment allocations.
Blockchain and Distributed Ledger Technology
Distributed ledger technology has moved from experimental pilot projects to production systems handling real financial transactions. Major financial institutions now use blockchain networks for cross-border payments, securities settlement, trade finance, and digital asset custody.
The technology offers several compelling advantages for financial operations:
- Settlement speed reduced from days to minutes or seconds
- Operational transparency through immutable transaction records
- Reduced intermediary costs by enabling peer-to-peer transactions
- Enhanced auditability with complete transaction histories
- Programmable money through smart contracts that execute automatically
Digital Assets and Tokenization
The tokenization of traditional financial assets represents a significant application of blockchain technology in finance. Real estate, corporate bonds, private equity stakes, and even fine art are being represented as digital tokens that can be fractionalized, traded, and settled on distributed networks.
Central banks worldwide are developing or piloting central bank digital currencies (CBDCs), which would represent government-issued money on blockchain infrastructure. These initiatives aim to combine the benefits of digital payments with the stability and regulatory oversight of traditional fiat currency.
| Asset Class | Tokenization Benefits | Implementation Challenges |
|---|---|---|
| Real Estate | Fractional ownership, 24/7 trading | Legal frameworks, property rights |
| Bonds | Faster settlement, reduced costs | Market fragmentation, standardization |
| Private Equity | Improved liquidity, broader access | Valuation complexity, regulatory clarity |
| Commodities | Supply chain transparency, efficiency | Physical custody, delivery mechanisms |
The Mills Review published by the UK’s FCA explores how digital assets, tokenisation, and blockchain will reshape retail financial services by 2030, examining both opportunities for innovation and emerging consumer protection concerns.
Cloud Computing and Infrastructure Modernization
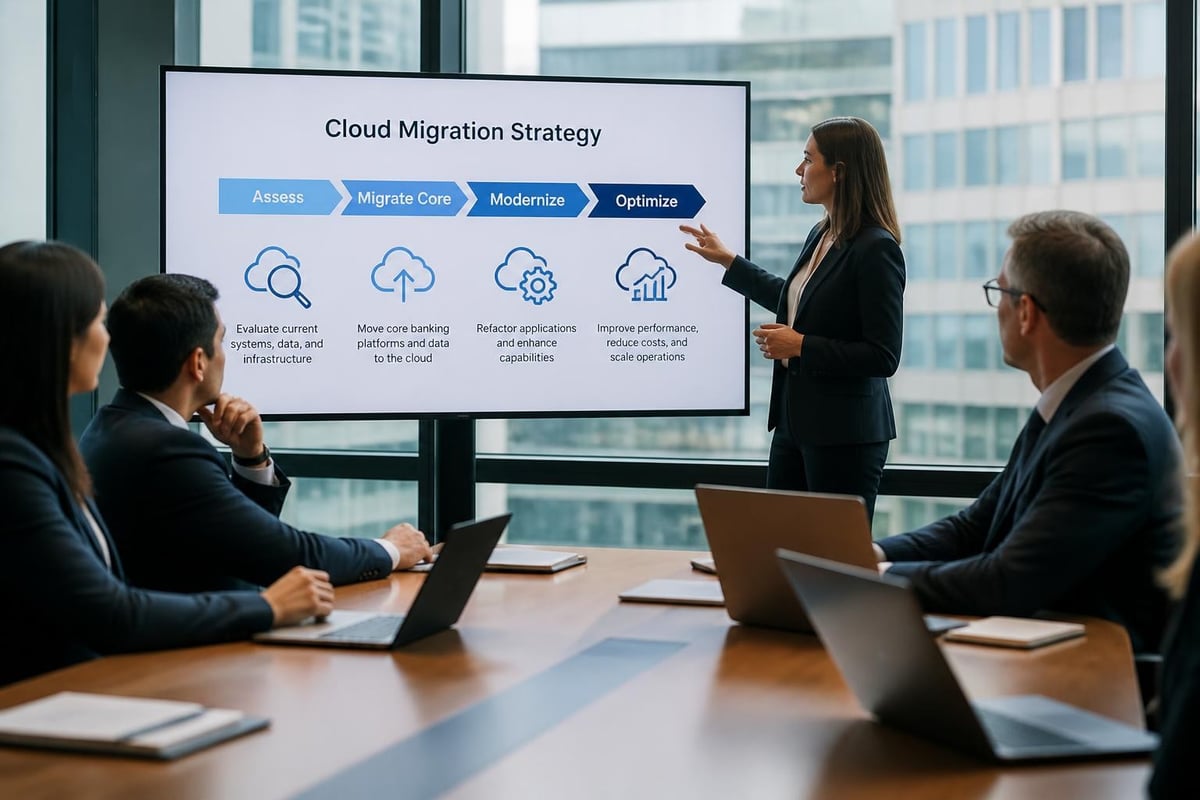
Cloud infrastructure has become the backbone of modern financial technology, enabling scalability, resilience, and rapid deployment of new capabilities. Financial institutions are migrating core banking systems, data warehouses, and customer-facing applications to cloud platforms operated by major technology providers.
This shift enables several critical capabilities:
- Elastic computing resources that scale automatically with demand
- Geographic distribution for disaster recovery and low-latency access
- Access to advanced AI and analytics tools integrated into cloud platforms
- Faster development cycles through cloud-native application architectures
- Reduced capital expenditure on data center infrastructure
However, cloud adoption in finance also introduces new risks around data sovereignty, vendor concentration, cybersecurity, and operational resilience when critical systems depend on external providers.
Payment Technology and Financial Inclusion
Technology in finance has dramatically expanded access to financial services for previously underserved populations. Mobile banking platforms, digital wallets, and peer-to-peer payment networks enable financial participation without traditional bank branches or extensive paperwork.
Real-Time Payment Systems
Countries worldwide have implemented real-time payment infrastructures that settle transactions instantly, 24 hours a day, every day of the year. These systems fundamentally change payment economics by eliminating float, reducing working capital requirements, and enabling new business models based on instant settlement.
In 2026, real-time payment volumes continue growing rapidly as businesses and consumers experience the benefits of immediate fund availability. The technology supports use cases from bill splitting among friends to just-in-time supplier payments in complex manufacturing supply chains.
The convergence of real-time payments with other technologies creates powerful new capabilities. When combined with AI-powered identity verification, blockchain-based smart contracts, and open banking APIs, payment systems become programmable infrastructure supporting automated, conditional, and intelligent money movement.
Regulatory Technology and Compliance
Regulatory technology (RegTech) applies advanced technology to compliance challenges that have grown increasingly complex and costly. Financial institutions face thousands of regulatory requirements across multiple jurisdictions, each with specific reporting formats, timelines, and standards.
Technology in finance now encompasses sophisticated compliance systems that:
- Monitor transactions in real-time for suspicious activity patterns
- Automatically generate regulatory reports in required formats
- Track regulatory changes and map them to internal controls
- Verify customer identities using biometric and document authentication
- Manage data privacy requirements across jurisdictional boundaries
The joint OECD, European Commission, and Banca d’Italia study on AI adoption in financial markets maps current practices and cross-country policy challenges, illustrating how regulators themselves are adapting to technology-driven market evolution.
For online publications covering the financial sector, opportunities exist to contribute analysis through platforms that accept expert perspectives, such as Guest Post submissions that help readers understand these complex technological and regulatory intersections.
Cybersecurity and Risk Management
As financial services become more digital, cybersecurity evolves from a technical concern to a strategic business imperative. Financial institutions face constant threats from sophisticated attackers seeking to steal funds, compromise customer data, or disrupt operations.
Modern financial cybersecurity relies on multiple technology layers:
- Zero-trust network architectures that verify every access request
- Behavioral analytics detecting anomalous user or system activity
- Encrypted communications protecting data in transit and at rest
- Automated threat response systems that contain breaches within milliseconds
- Continuous security testing through simulated attack scenarios
| Security Technology | Primary Function | Key Benefit |
|---|---|---|
| Multi-factor authentication | Identity verification | Reduces account takeover |
| Tokenization | Data protection | Limits breach exposure |
| Security orchestration | Incident response | Faster threat containment |
| Threat intelligence | Attack prevention | Proactive defense |
The financial consequences of security failures have grown alongside digital adoption, making cybersecurity investments essential rather than optional for institutions handling customer assets and sensitive financial data.
Open Banking and API Ecosystems
Open banking regulations require financial institutions to provide secure API access to customer data and payment initiation capabilities for authorized third parties. This regulatory-driven technology shift transforms banks from closed systems into platforms that enable ecosystem innovation.
Through standardized APIs, customers can securely share their financial data with budgeting apps, lending platforms, investment advisors, and other services that provide enhanced value. Payment initiation APIs enable merchants and service providers to trigger bank transfers directly, creating alternatives to traditional card networks.
The technology in finance supporting open banking includes:
- OAuth 2.0 and OpenID Connect for secure authorization
- RESTful APIs with standardized data schemas
- Developer portals and sandbox environments for testing
- Real-time data synchronization protocols
- Consent management dashboards for customer control
This ecosystem approach accelerates innovation by allowing specialized fintech companies to build on banking infrastructure without becoming banks themselves, while customers benefit from integrated financial experiences across multiple providers.
Quantum Computing and Future Technologies
While still largely experimental, quantum computing represents a potential paradigm shift for technology in finance. Quantum algorithms could revolutionize portfolio optimization, derivative pricing, fraud detection, and cryptographic security, though practical implementations remain years away for most applications.
A comprehensive literature review in Financial Innovation surveys emerging technologies including quantum computing alongside AI, blockchain, and augmented reality, mapping their potential use cases across financial services.
Financial institutions are monitoring quantum developments closely because the technology also threatens current encryption standards. “Quantum-safe” cryptography development has become a priority to protect financial communications and stored data against future quantum attacks that could break today’s encryption methods.
Emerging Technology Landscape
Beyond quantum computing, several other technologies show promise for financial applications:
- Edge computing for ultra-low-latency trading and payment processing
- 5G networks enabling mobile banking in previously unconnected regions
- Augmented reality for immersive customer service and financial planning
- Internet of Things generating real-time data for insurance pricing and lending decisions
- Synthetic data creating realistic datasets for AI training while protecting privacy
The convergence of these technologies creates compound effects, where combinations deliver more value than individual technologies in isolation. For instance, IoT sensors combined with blockchain and AI enable parametric insurance that automatically pays claims when predefined conditions occur, verified through immutable sensor data.
Workforce Transformation and Skills
Technology in finance has fundamentally changed workforce requirements within financial institutions. Traditional finance skills remain important, but they now combine with data science, software engineering, cybersecurity, and digital product management capabilities.
Financial institutions compete intensely for technology talent with pure technology companies, often at a disadvantage due to legacy systems, regulatory constraints, and organizational culture. This talent competition drives compensation inflation and prompts investments in training programs that upskill existing employees.
The shift toward automated decision-making and digital customer interaction also raises questions about employment levels in financial services. While technology eliminates some routine tasks, it simultaneously creates demand for roles managing AI systems, analyzing complex data, designing digital experiences, and ensuring regulatory compliance in technology-enabled processes.
Readers interested in exploring broader technology trends can find related coverage at Fairmont Post, which examines how technological innovation reshapes multiple sectors beyond finance.
Data Strategy and Analytics
Data has become the most valuable asset for financial institutions pursuing technology-enabled transformation. Every customer interaction, transaction, market movement, and operational event generates data that, when properly analyzed, produces insights driving better decisions.
Modern financial data strategies encompass:
- Unified data platforms consolidating information from disparate source systems
- Real-time data pipelines enabling immediate analysis and action
- Data governance frameworks ensuring quality, security, and regulatory compliance
- Advanced analytics capabilities extracting patterns and predictions from massive datasets
- Data monetization strategies creating new revenue streams from proprietary information
The challenge extends beyond technology to organizational structure. Many financial institutions operate data silos across business lines, with inconsistent definitions, formats, and quality standards that impede comprehensive analysis. Breaking down these silos requires both technical integration and cultural change.
Customer Experience and Digital Engagement
Technology in finance ultimately serves to enhance customer experiences, whether through more convenient access, personalized recommendations, faster service, or better financial outcomes. Digital-first customers expect seamless, intuitive interactions across devices and channels, with instant access to account information and immediate transaction execution.
Financial institutions invest heavily in:
- Mobile applications offering full banking functionality
- Personalized dashboards surfacing relevant insights and recommendations
- Chatbots and virtual assistants providing 24/7 support
- Biometric authentication eliminating passwords and PINs
- Proactive alerts about unusual activity or optimization opportunities
The most successful digital experiences in finance combine sophisticated technology with deep understanding of customer needs and behaviors. Technology enables personalization at scale, delivering contextually relevant information and offers to millions of customers based on their unique financial situations and goals.
Technology in finance continues evolving at an unprecedented pace, reshaping how financial services are delivered, regulated, and experienced. From AI-powered decision systems to blockchain settlement networks and cloud infrastructure, these technologies create both opportunities and challenges for institutions, regulators, and customers. For comprehensive coverage of how technological innovation intersects with finance, business, and other sectors, Fairmont Post delivers insights and analysis on the trends shaping our digital economy.


